UK Casinos That Accept Pay N Play: The Reality Behind Instant Banking in 2026
 Available in US
Pay N Play arrived in the UK casino market with a promise that sounded too good to be true: deposit from your bank, start playing instantly, withdraw your winnings in minutes, all without filling in a registration form or uploading a single document. For players tired of multi-day verification queues and card number anxiety, it felt like the answer.
The reality in 2026 is more complicated. The Gambling Commission does not do anonymous gambling. It requires full know-your-customer checks before you place a single bet, which means the Swedish “no registration” model that made Pay N Play famous does not transplant cleanly to British soil. What you get instead is Trustly instant banking: your bank verifies your identity in seconds via Open Banking APIs, the casino creates your account in the background, and you start playing faster than at a traditional site. Instant, yes. Registration-free, no.
This guide covers which UKGC-licensed casinos accept Pay N Play deposits and withdrawals in 2026, how the method actually works under UK rules, what “instant withdrawal” really means once affordability checks enter the picture, and where Trustly sits in the broader payment landscape. Eleven operators feature with substantive breakdowns—LeoVegas, Casumo, Mr Green, Unibet, Betsson, Rizk, Videoslots, William Hill, Duelz, 888 Casino, and MrQ—each profiled on withdrawal speed, bonus eligibility, and the specific open-banking rail they use. No fluff, no invented statistics, no pretending GamStop does not exist.
What Pay N Play Actually Means in the UK (2026)
Pay N Play is Trustly’s branding for a casino onboarding flow that compresses registration, age verification, and first deposit into a single step. You pick your bank, log in with your usual biometrics or PIN, approve the payment, and start playing. The casino receives your verified name, date of birth, and address directly from the bank, creates your account behind the scenes, and credits your deposit. In Sweden and Finland, where Trustly launched the product in 2015, this works as advertised: no form, no email confirmation loop, genuinely instant play.
The UK version differs in one critical respect. Licence Condition 17 of the UKGC’s code of practice mandates that operators verify customer identity and age before any gambling takes place, and that verified data be held in a full player account integrated with GamStop, transaction monitoring, and responsible gambling tools. Trustly’s bank-ID verification satisfies the identity and age requirements—your bank has already performed KYC when you opened the account, and the Open Banking API passes that verified data through—but the Gambling Commission does not permit a “session-only” model with no persistent account. The casino must create a full registered account, tie it to your verified identity, and check you against the GamStop self-exclusion register before you can gamble.
Practically, this means UK “Pay N Play” casinos still create an account for you. The difference from traditional registration is that you never see the form. You do not choose a username or password, you do not type in your address, you do not wait for an email confirmation link. The casino uses the bank-verified data to generate your account in the background and logs you in automatically. When you return, you “log in” by making another Trustly deposit—the system recognizes your bank account and restores your session. Some operators let you set a password later for traditional login; others keep you in deposit-triggered sessions permanently.
The phrase “no registration” is marketing shorthand for “no manual form-filling,” not a literal absence of an account. Every UK-licensed Pay N Play casino holds your data, tracks your transactions, applies deposit limits, and integrates with GamStop. The convenience gain is real—most players go from landing page to first spin in under two minutes—but the regulatory obligations do not disappear just because Trustly automates the data flow.
What is the difference between Pay N Play and regular Trustly deposits?
Pay N Play uses Trustly’s bank-ID verification to automate account creation at a casino. Regular Trustly deposits are simply a payment method at a casino where you already have a registered account. The underlying technology—Open Banking, bank authentication, Faster Payments—is identical. The difference is whether the casino uses Trustly data to skip the registration form or treats it as a deposit rail only.
Do UK casinos offer Pay N Play with no registration?
No UK casino can offer truly registration-free gambling. UKGC rules require a full player account integrated with GamStop and transaction monitoring before any bet is placed. What UK casinos call “Pay N Play” is automated registration via Trustly bank verification, not an absence of registration. You still have an account; you just never filled in the form manually.
The technical flow matters because it shapes what happens after your first deposit. Trustly verification covers your identity and age—enough to satisfy Licence Condition 17’s baseline requirement—but it does not automatically satisfy anti-money laundering checks on source of funds. If you deposit £500 in your first session, or accumulate £1,000 over a few days, the casino’s AML system may flag your account for additional verification. At that point, you receive an email asking for proof of address, a bank statement, or documentation of your income source. The Trustly verification bought you speed on day one, but it did not eliminate the possibility of document requests later.
This is not a Trustly failure. It is the Gambling Commission’s tiered verification framework at work. Bank-ID checks cover identity theft and underage gambling. Source-of-funds checks cover money laundering and gambling harm. Trustly handles the first; the casino’s compliance team handles the second when thresholds trigger. Competitors who claim “instant withdrawals, no verification” are either describing the best-case path for small-stakes players or underselling the reality that every UK operator must perform enhanced due diligence on higher-value customers regardless of payment method.
The distinction between TrueLayer, Plaid, and Trustly adds another layer. LeoVegas brands its open-banking option as “TrueLayer,” PokerStars uses “Plaid Payouts,” bet365 labels it “Trustly,” and smaller operators sometimes call it “Instant Bank Transfer” with no brand name at all. From a regulatory and technical standpoint, these are functionally identical: all connect via Open Banking APIs, all authenticate via your bank app, all settle via Faster Payments. Trustly, TrueLayer, and Plaid are simply different payment service providers offering the same underlying infrastructure. The user experience is indistinguishable. If you have used one, you have used them all.
This matters because “Pay N Play” has become synonymous with Trustly in affiliate marketing, which creates confusion when a player sees “TrueLayer” or “Plaid” in a cashier and assumes the casino does not support instant banking. It does. The brand on the button is an implementation detail; the flow—bank login, instant verification, automated account creation—is the same.
UK Casinos That Accept Pay N Play in 2026
The table below lists the eleven UKGC-licensed casinos with confirmed Trustly, TrueLayer, or Plaid integration as of 2026. All hold active remote gambling licences verified on the Gambling Commission’s public register. Withdrawal speed reflects typical processing time after the casino approves the payout; the Faster Payments leg itself settles in seconds, but internal approval queues vary by operator and account status.
| Operator | UKGC Licence | Withdrawal Speed | Min Deposit | Distinguishing Feature |
|---|---|---|---|---|
| LeoVegas | 000-039483-R-319346-013 | Under 1 hour | £10 | TrueLayer rail, mobile-first, MGM ownership |
| Casumo | 000-038117-R-319373-017 | Same-day to next morning | £10 | Gamification (adventure system), 30x wagering |
| Mr Green | 000-039264-R-319449-001 | Same-day after first verification | £10 | Green Gaming predictive responsible gambling tool |
| Unibet | 000-039483-R-319502-001 | Under 12 hours | £5 | Unified sportsbook-casino wallet, Kindred Group |
| Betsson | Multiple (group licences) | Hours after approval | £10 | Multi-brand platform, transparent bonus terms |
| Rizk | Confirmed on register | Same-day | £10 | Wheel of Rizk reward mechanic, Kindred ownership |
| Videoslots | 000-039483-R-319661-004 | Hours after approval | £10 | 4,000+ slots, 10x bonus wagering (lowest in UK) |
| William Hill | 000-039225-R-319647-001 | Hours after approval | £10 | Heritage brand (founded 1934), Evoke ownership |
| Duelz | Confirmed on register | Same-day | £25 | Tournament/duels mechanic, Rootz Ltd |
| 888 Casino | 000-039372-R-319314-001 | Same-day after approval | £10 | Proprietary 888-exclusive slots, integrated poker |
| MrQ | 000-053660-R-330388-001 | Same-day | £10 | Zero wagering on all bonuses (unique in UK) |
Withdrawal speed assumes you have already passed initial KYC. First-time withdrawals at any UK casino may trigger additional document requests regardless of payment method, especially if cumulative deposits exceed £1,000 or if the casino’s risk model flags unusual patterns. Once your account clears enhanced due diligence, subsequent withdrawals via Trustly or its equivalents typically land within the timeframes shown.
The distinguishing feature column highlights what sets each operator apart in practical terms. LeoVegas owns the mobile experience. Casumo adds gamification. Mr Green leads on responsible gambling tools. Videoslots offers the deepest slots catalogue and the lowest bonus wagering in the UK market. MrQ is the only operator where every bonus and free spin carries zero wagering requirements—winnings are credited as withdrawable cash, no rollover. These are not marketing angles; they are structural differences that matter when picking where to play.
LeoVegas: Mobile-First with TrueLayer Speed
LeoVegas operates under UKGC licence 000-039483-R-319346-013, held by LeoVegas Gaming Ltd. The brand built its reputation as the “King of Mobile Casino” and was acquired by MGM Resorts International in 2022 for approximately $607 million. The UK operation launched in 2016 and integrated TrueLayer for open banking around 2020. The cashier labels it “Open Banking” rather than “Trustly” or “Pay N Play,” but the flow is identical: pick your bank, authenticate in your app, start playing.
The mobile app remains best-in-class. iOS and Android versions carry 4+ star ratings, and the interface is built mobile-first rather than desktop-shrunk. The game library spans 1,000+ slots and 100+ live dealer tables from Evolution and Pragmatic Live, with a sportsbook integrated into the same wallet. TrueLayer withdrawals clear in under an hour after approval for most players—among the fastest in the UK market. Minimum deposit is £10. The welcome offer is a standard deposit match with free spins at 35x wagering; TrueLayer deposits qualify without restriction, unlike the Skrill and Neteller exclusions common at competitors.
LeoVegas suits players who treat mobile as primary and want sub-hour withdrawals without upgrading to VIP tiers. The MGM acquisition brought group infrastructure but left the brand identity intact. Document requests on first withdrawal are rare unless deposits exceed £1,000 in aggregate; the TrueLayer bank verification satisfies most compliance checks upfront.
Casumo: Gamification Meets Same-Day Payouts
Casumo operates under UKGC licence 000-038117-R-319373-017, held by Casumo Services Ltd. Founded in Malta in 2012, the brand launched UK operations in 2015 and remains an independent operator—not part of a larger multi-brand group. The standout feature is the “Casumo adventure” gamification layer: players earn points and unlock trophies for deposits, gameplay milestones, and session activity. It is cosmetic but sticky; the progression system adds a light RPG wrapper to standard casino mechanics.
The game library runs to 3,500+ titles, covering slots from NetEnt, Microgaming, Play’n GO, Pragmatic Play, and live dealer tables from Evolution. Trustly integration is branded as “Trustly” or “Instant Banking” in the cashier. Deposits settle instantly with a £10 minimum. Withdrawals via Trustly typically land same-day or next morning—within 24 hours of approval. The welcome bonus is a 100% match plus 100 free spins, notable for 30x wagering rather than the 35–40x more common in the UK. Trustly deposits qualify for bonuses without carve-outs.
Casumo fits players who want depth (3,500+ games) and lower wagering requirements without sacrificing withdrawal speed. The gamification is take-it-or-leave-it; the core offering—game variety, bonus terms, Trustly speed—stands on its own. Same-day payouts are reliable but not quite as fast as LeoVegas’s sub-hour norm.
Mr Green: Green Gaming Responsible Tools
Mr Green operates under UKGC licence 000-039264-R-319449-001, held by Mr Green Ltd. The brand launched in Sweden in 2008, entered the UK in 2012, and was acquired by William Hill in 2019. William Hill itself merged with 888 Holdings in 2022 to form Evoke plc, so Mr Green now sits within one of Europe’s largest gambling conglomerates. The defining feature is Green Gaming, a predictive responsible gambling tool that monitors play patterns in real time and intervenes with reality checks, limit suggestions, and cooling-off prompts before harm patterns solidify.
The casino library spans 1,500+ games with a strong live dealer section powered by Evolution. Trustly is branded as “Trustly” in the cashier. Deposits are instant, £10 minimum. Withdrawals via Trustly typically land same-day after approval, though first withdrawals may trigger a document upload request if cumulative deposits exceed £1,000. The welcome bonus is a match with free spins at standard 35x wagering; Trustly deposits qualify. Green Gaming adds friction by design—if the algorithm flags risky play, you see a mandatory pause and limit suggestion. For some players, this is paternalism; for others, it is exactly the guardrail they need.
Mr Green suits players who value responsible gambling features above all else or who trust the William Hill/Evoke brand infrastructure. The Trustly integration is solid but not the fastest. The Green Gaming tool is the standout; if you want proactive intervention rather than reactive limits, this is the operator built for it.
Unibet: Unified Sportsbook and Casino Wallet
Unibet operates under UKGC licence 000-039483-R-319502-001, held by Trannel International Ltd. The brand is part of Kindred Group plc, a publicly traded Swedish operator listed on Nasdaq Stockholm. Unibet launched in 1997 and entered the UK market in the early 2000s. The sportsbook is the primary focus—one of Europe’s largest by market share—but the casino offering is substantial, with 1,000+ slots, live dealer tables from Evolution and NetEnt Live, and a unified wallet that lets you move funds between sports and casino without friction.
Trustly is branded as “Trustly” or “Bank Transfer” in the cashier. Deposits are instant with a £5 minimum (lower than most competitors). Withdrawals via Trustly typically clear in under 12 hours after approval. The casino welcome bonus is modest—a deposit match with free spins—but wagering is often 25–30x, lower than the 35–40x norm. Headline value is smaller; rollover is friendlier. Trustly deposits qualify for bonuses. The unified wallet is the key differentiator: if you bet on football and play slots in the same session, Unibet handles it as one balance with no transfer steps.
Unibet suits players who want a single account for sports and casino rather than splitting funds across separate sites. The sportsbook is the strength; the casino is solid but secondary. Trustly withdrawal speed is good—sub-12-hour is faster than traditional bank transfer but slower than LeoVegas or Casumo.
Betsson: Multi-Brand Platform with Transparent Terms
Betsson operates under multiple UKGC licences covering its brand portfolio. The main casino brand is Betsson, but the group also runs Betsafe, NordicBet, and CasinoEuro on shared infrastructure in the UK. Betsson AB is publicly traded on Nasdaq Stockholm and traces its roots to 1963 in Sweden, originally as offline betting shops. Online operations launched in the late 1990s. The group operates 20+ brands across Europe and Latin America; the UK portfolio is a small slice of global operations.
The casino library exceeds 2,000 games, with an extensive slots catalogue and strong live dealer coverage from Evolution and Pragmatic Live. Trustly is branded as “Trustly” in the cashier across all group brands. Deposits are instant, £10 minimum. Withdrawals via Trustly typically land within hours after approval—same-day is standard. The welcome bonus is a deposit match with free spins at 35x wagering; bonus terms are notably transparent, with no hidden gotchas buried in subsection clauses. Trustly deposits qualify. If you like the Betsson experience, the same login works across Betsafe and the other group brands—useful for sampling different bonus offers or game catalogues without creating separate accounts.
Betsson fits players who want reliability over flash. The multi-brand infrastructure offers variety, the Trustly integration is rock-solid, and the transparent bonus terms eliminate the fine-print anxiety common at smaller operators. No single standout feature, but nothing weak either. Scandinavian heritage means Trustly was native from the start, not bolted on later.
Rizk: Wheel of Rizk Reward Mechanic
Rizk operates under a confirmed UKGC licence held by MT SecureTrade Ltd. The brand launched in Malta in 2016 and was acquired by Kindred Group in 2017, making it a sister brand to Unibet within the same corporate structure. UK operations launched in 2017. The defining feature is the Wheel of Rizk: after hitting certain gameplay milestones, players spin a reward wheel for free spins, bonuses, or cash prizes. It is proprietary gamification, less elaborate than Casumo’s adventure system but more tangible than standard loyalty points.
The game library runs to 1,500+ titles, strong on slots from NetEnt, Play’n GO, and Microgaming, with Evolution-powered live dealer tables. Trustly is branded as “Trustly” in the cashier. Deposits are instant, £10 minimum. Withdrawals via Trustly typically land same-day after approval. The welcome bonus is a deposit match with free spins, wagering at 40x—on the higher side compared to competitors. Trustly deposits qualify. The Wheel of Rizk adds an element of chance to rewards: some spins give modest free-spin bundles, others drop significant cash bonuses. Variance works both ways.
Rizk suits players who like gamification but want something simpler than Casumo’s multi-tier adventure. The Kindred ownership brings group infrastructure and the same backend as Unibet. Same-day Trustly withdrawals are reliable. The 40x wagering on the welcome bonus is a drawback; compare terms before claiming.
Videoslots: Deepest Slots Library in the UK
Videoslots operates under UKGC licence 000-039483-R-319661-004, held by Videoslots Ltd. The brand launched in Malta in 2011, entered the UK in 2014, and remains an independent operator—not owned by a larger group. The standout feature is the slots catalogue: 4,000+ titles from 100+ providers, one of the deepest libraries in the UK market. Table games and live dealer options exist, but slots are the focus. The “Battle” feature adds slot tournaments with real-money prizes—competitive leaderboard play rather than solo spins.
Trustly integration is sometimes labeled “Pay N Play” in marketing materials, though the UK version still requires full account creation per UKGC rules. Deposits are instant, £10 minimum. Withdrawals via Trustly typically land within hours after approval. The welcome bonus is £50 with 10x wagering—the lowest rollover requirement in the UK. Most competitors sit at 35–40x; Videoslots dropped to 10x in 2024, a significant competitive advantage. Trustly deposits qualify. The low wagering makes the bonus terms player-friendly; the shallow requirement means more bonus value converts to withdrawable cash.
Videoslots fits players who prioritize slots variety above all else and who want usable bonus terms. The 4,000-title catalogue covers every provider from household names to obscure studios. The 10x wagering on the welcome bonus is unmatched. Tournament play via Battles adds a competitive angle. Independent ownership means no cross-brand promotions, but the core offering—depth, bonus terms, Trustly speed—is strong.
William Hill: Heritage Brand with Fast Trustly Payouts
William Hill operates under UKGC licence 000-039225-R-319647-001, held by WHG (International) Ltd. The brand was founded in 1934 as a UK bookmaker with retail betting shops and remains one of the most recognized gambling names in Britain. The online operation launched in the late 1990s. Caesars Entertainment acquired William Hill in 2018, Apollo Global Management took over in 2021, and the business merged with 888 Holdings in 2022 to form Evoke plc. The retail network still operates, though reduced post-merger. Sportsbook remains the primary focus; the casino is a substantial secondary offering.
The casino library spans 1,000+ slots and live dealer tables from Evolution and Playtech Live. Trustly is branded as “Pay N Play” or “Trustly” in the cashier. Deposits are instant, £10 minimum. Withdrawals via Trustly are reported as fast—hours after approval. The welcome offer is unusual: 200 free spins on Big Bass Splash for a £10 deposit, no match bonus. Winnings are capped at £30 and expire in 72 hours, but there is no wagering requirement. Trustly deposits qualify. The structure favors small-stakes players who want a no-strings trial over large-balance chasers.
William Hill suits players who value brand recognition and heritage over cutting-edge features. The 88-year UK presence adds trust. The Trustly integration is solid. The free spins offer is polarizing—either you like the no-wagering simplicity or you find the £30 cap restrictive. The Evoke group infrastructure brings stability; the William Hill name brings familiarity.
Duelz: Tournament-Focused Casino
Duelz operates under a confirmed UKGC licence held by Rootz Ltd. The brand launched in Malta in 2019 as part of the Rootz portfolio, which also operates Wheelz and Wildz casinos. UK operations launched in 2020. The distinguishing feature is the tournament and duels system: competitive leaderboards and head-to-head slot challenges where players compete for prizes. It is more elaborate than Rizk’s wheel but less narrative-driven than Casumo’s adventure.
The game library exceeds 3,000 titles, covering slots from NetEnt, Play’n GO, Pragmatic Play, and live dealer tables from Evolution. Trustly integration is branded as “Pay N Play” or “Instant Banking.” Deposits are instant with a £25 minimum—higher than the £10 norm at most competitors. Withdrawals via Trustly typically land same-day. The welcome bonus structure is multi-day: up to 140 free spins (20 per day for 7 consecutive days), manually claimed each day or they expire at midnight. Spins are £0.10 each, max £100 winnings per day credited as bonus with 10x wagering. Trustly deposits qualify.
Duelz fits players who want competitive mechanics—leaderboards, duels, tournament play—over solo spins. The £25 minimum deposit is a barrier for small-stakes players. The multi-day free spins structure requires daily engagement; miss a day and you forfeit that batch. Rootz is a small independent group, so no cross-brand infrastructure, but the platform is stable. Same-day Trustly withdrawals are reliable.
888 Casino: Established Brand with Proprietary Content
888 Casino operates under UKGC licence 000-039372-R-319314-001, held by 888 UK Ltd. The brand launched in 1997 and is one of the first licensed online casinos still operating. 888 Holdings went public on the London Stock Exchange in 2005, later moved to Nasdaq Stockholm, and merged with William Hill in 2022 to form Evoke plc. The UK operation has been UKGC-licensed continuously since the regulator’s inception. The standout feature is proprietary content: 500+ 888-exclusive slots alongside third-party titles, bringing the total library to 1,500+. The live dealer offering includes both 888 Live (proprietary) and Evolution tables. The integrated poker room—888poker—is one of the world’s top three poker networks by traffic.
Trustly integration is branded as “Instant Bank Transfer” or similar. Deposits are instant, £10 minimum. Withdrawals via Trustly typically land same-day after approval. The welcome offer is 100 free spins on Big Bass Splash for a £10 deposit, with a £10 slots play requirement to unlock them. Spins expire in 48 hours. Winnings carry no wagering and are credited as cash. Trustly deposits qualify. The no-wagering structure is strong—winnings are immediately withdrawable. The 48-hour expiry is tight but standard for UK free spin offers.
888 Casino suits players who want an established operator with 27 years of track record and who value proprietary content. The 888-exclusive slots differentiate the catalogue from competitors running only third-party content. The integrated poker room is a draw for poker players. Evoke ownership brings group scale. Trustly withdrawals are same-day, though not sub-hour like LeoVegas.
MrQ: Zero Wagering on All Bonuses
MrQ operates under UKGC licence 000-053660-R-330388-001, held by Lindar Media Ltd, a UK-based operator. The brand launched in 2018 and implemented a zero-wagering model from the start: all bonuses and free spins carry no rollover requirement. Winnings are credited as withdrawable cash immediately. This is nearly unique in the UK market; most operators impose 35–40x wagering. MrQ’s model eliminates rollover but offers smaller headline bonuses to compensate.
The game library is curated rather than exhaustive—500+ slots focusing on popular titles like Starburst, Fishin’ Frenzy Megaways, and Cleopatra. The live dealer section is smaller than at major competitors. A bingo room is integrated. Trustly is branded as “Pay N Play” or “Bank Transfer.” Deposits are instant, £10 minimum. Withdrawals via Trustly are same-day. The welcome offer is 100 free spins for a £10 deposit on Big Bass Splash, £0.10 per spin, 48-hour expiry, zero wagering. Winnings are cash, immediately withdrawable. Trustly deposits qualify. Northern Ireland players are excluded from certain offers due to regional gambling regulations.
MrQ suits players who prioritize usable bonus terms over catalogue depth. The zero-wagering model is the standout differentiator. The game library is smaller but covers mainstream hits. UK-based ownership is a trust signal for some players. Trustly same-day withdrawals are reliable. If you have been burned by high-wagering bonuses that never convert, MrQ’s model is the antidote.
How to Deposit and Withdraw with Pay N Play at UK Casinos
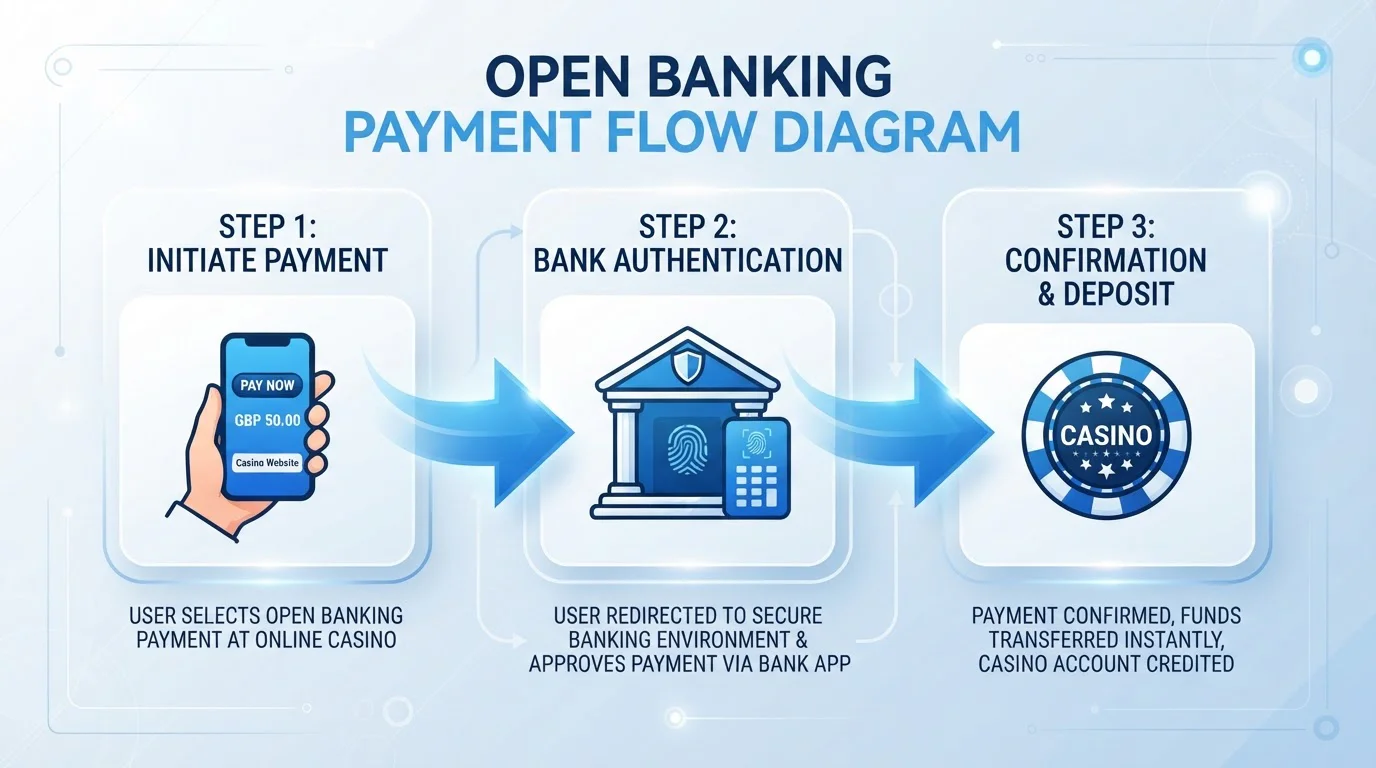
The deposit flow at a UK Pay N Play casino compresses what would normally be three separate steps—registration, verification, and payment—into a single interaction lasting under two minutes. You land on the casino, click the deposit or “Play Now” button, enter the amount you want to deposit, and select Trustly, TrueLayer, Plaid, or whichever open-banking option the cashier displays. The system redirects you to a selection screen listing UK banks. You pick your bank.
At this point, you leave the casino’s environment and enter your bank’s app or web interface. You authenticate using whatever method your bank requires: biometrics, PIN, password, or two-factor authentication. The bank shows you the payment details—recipient (the casino), amount, and a consent notice explaining that you are authorizing both the payment and the sharing of verified identity data with the merchant. You approve. The Open Banking API transmits your verified name, date of birth, and address to Trustly (or TrueLayer, or Plaid), which forwards it to the casino along with payment confirmation. The casino’s backend receives the data, checks you against the GamStop register, creates your account if you are a new player or matches you to an existing account if returning, credits your balance, and logs you in. You land back on the casino site with funds in your account. Total elapsed time: typically 60–120 seconds.
The speed comes from automation. Your bank has already verified your identity when you opened the account. The Open Banking framework—mandated in the UK since 2018 under the Payment Services Regulations—allows third parties like Trustly to request verified data directly from your bank via API, eliminating the need for you to manually enter or upload anything. The casino receives data it can trust because it comes from a regulated financial institution, not a user-submitted form. This satisfies the UKGC’s Licence Condition 17 requirement for customer identity verification while removing the friction of manual document uploads.
Returning to the same casino is even faster. Most UK Pay N Play casinos implement “login via deposit”: you do not set a username or password during initial registration, so when you return, you click deposit, select your bank, and authenticate. The system recognizes your bank account, matches it to your existing player account, and logs you in. Some operators offer the option to set a traditional username and password after your first session if you prefer login without triggering a deposit; others keep you in deposit-triggered sessions permanently. Either way, your account persists with full transaction history, balance, deposit limits, and GamStop integration. The “no account” marketing is shorthand for “no manual form”; the account itself exists and is subject to all UKGC obligations.
Making Your First Deposit
Minimum deposits at the eleven operators range from £5 (Unibet) to £25 (Duelz), with £10 being the most common. The Open Banking APIs do not impose transaction minimums; the floor is set by each casino’s payment policy. Maximum deposits per transaction vary by operator and by your bank’s own limits. Faster Payments, the UK bank transfer scheme that settles Open Banking transactions, supports up to £1,000,000 per transaction at the scheme level, but most casinos cap individual deposits at £5,000–£10,000 for anti-money laundering reasons. If you want to deposit more, you split it across multiple transactions or request a limit increase from customer support, which typically triggers enhanced due diligence.
Deposits credit instantly. The Open Banking flow completes in seconds, and the Faster Payments settlement is near-instant. There is no pending state. You approve in your bank app, and by the time you return to the casino, the funds are in your balance. This is faster than debit cards, which can take several minutes to authorize, and far faster than traditional bank transfers, which take one to three business days.
One practical catch: if you make a large first deposit—say £500 or more—or if you accumulate deposits exceeding £1,000 within a short period, the casino’s AML system may flag your account for source-of-funds verification even though the Trustly bank-ID check has already confirmed your identity and age. You can play with the deposited funds immediately, but before you can withdraw, you may receive an email requesting proof of income, a recent bank statement, or documentation explaining the origin of the funds. This is not a Trustly limitation; it is the UKGC’s tiered verification framework at work. Bank-ID satisfies baseline identity checks but does not substitute for enhanced due diligence on higher-value transactions. The threshold varies by operator; £1,000 in cumulative deposits within 30 days is a common trigger point.
Withdrawal Process and Timing
Withdrawals via Trustly or its equivalents use the same Faster Payments rail as deposits but in reverse. You request a withdrawal in the casino cashier, select Trustly as the method, and the funds are pushed back to the bank account you deposited from. UK gambling regulations mandate “closed-loop” payments: withdrawals must return to the same source as the deposit unless that source is no longer available, in which case you provide alternative verification. This prevents money laundering through payment method switching.
The advertised withdrawal speed—”under 1 hour” at LeoVegas, “same-day” at Casumo, “hours” at Videoslots—refers to the time between the casino approving your withdrawal and the funds landing in your bank account. The Faster Payments leg itself settles in seconds. The variable is the casino’s internal approval queue. Operators with automated approval systems for pre-verified accounts can release Trustly withdrawals in minutes. Operators with manual compliance reviews may take several hours or, in worst cases, up to 24 hours even for straightforward requests.
First withdrawals almost always take longer. Even if you deposited via Trustly and the bank-ID verification passed, the casino’s compliance team typically reviews your first withdrawal manually. This is where additional document requests most commonly appear. If your deposits have been modest—say £50–£200—and you have verified your identity via Trustly, the first withdrawal may clear without additional documents. If deposits exceed £1,000, or if your account activity triggers any AML flags (rapid deposit-and-withdrawal cycles, unusual play patterns, large wins), expect an email asking for proof of address, a recent bank statement, or source-of-funds documentation. You upload the documents through the cashier or email them to support; the compliance team reviews within 24–72 hours; once approved, your withdrawal processes and subsequent withdrawals are typically much faster.
This is not deceptive; it is the regulatory reality. The Gambling Commission requires operators to perform enhanced due diligence on customers who meet certain thresholds. Trustly’s bank-ID check covers identity and age but does not eliminate the need for source-of-funds verification. Competitors who advertise “instant withdrawals, no verification” are either describing the post-verification experience for small-stakes players or underplaying the initial compliance step.
After your first withdrawal clears, subsequent Trustly withdrawals are typically as fast as advertised. LeoVegas with TrueLayer often delivers sub-hour payouts. Casumo, Mr Green, and Betsson typically process same-day. Unibet under 12 hours. The Faster Payments rail itself is instant; the casino’s approval is the bottleneck. VIP or high-value players sometimes receive expedited approval, but for standard accounts, the speeds in the comparison table reflect realistic expectations once the initial verification hurdle is cleared.
When Document Checks Still Apply
Trustly bank-ID verification covers identity and age. It does not cover affordability or source of funds. The UKGC’s customer interaction requirements, tightened in recent years, obligate operators to assess whether customers are gambling with money they can afford to lose. This assessment can be automated for low-value players using open-source income data and statistical models, but above certain thresholds, manual review is required.
If you deposit £2,000 in your first week, or if you lose £500 in a single session, the casino’s system will almost certainly flag your account for enhanced interaction. You may receive a reality check, a request to set deposit limits, or a direct question about the source of the funds. If you ignore these prompts or if the amounts escalate, the casino will freeze withdrawals until you provide documentation—typically recent bank statements, payslips, or tax returns showing that the gambling expenditure is within your means.
This happens even at Pay N Play casinos. The Trustly verification streamlines onboarding, but it does not exempt the operator from affordability obligations. The bank knows your identity; it does not report your income to the casino. The casino must make that determination independently, and at higher stakes, that means requesting documents. If you plan to deposit more than £1,000 or play at stakes where a bad session could cost several hundred pounds, expect enhanced due diligence regardless of payment method.
The threshold varies by operator and by the sophistication of their risk models. Some casinos trigger manual review at £500 cumulative deposits; others at £2,000. Some use behavioral flags—rapid deposit-withdraw cycles, late-night high-stakes sessions, chasing losses—rather than fixed thresholds. The point is that no UK casino, Pay N Play or otherwise, can offer genuinely verification-free gambling above trivial stakes. The Gambling Commission’s rules do not permit it.
How fast are Trustly withdrawals at UK casinos?
Trustly withdrawals typically settle within minutes to a few hours once the casino approves the payout. The Faster Payments rail itself is near-instant; the variable is the casino’s internal approval queue. First withdrawals take longer due to compliance checks. After initial verification, LeoVegas often delivers under 1 hour, Casumo same-day, and most operators within 12 hours.
Why do some UK casinos still ask for documents even with Trustly verification?
Trustly bank-ID verification covers identity and age but not source of funds or affordability. UKGC rules require casinos to perform enhanced due diligence on customers who exceed certain deposit thresholds or exhibit risk indicators. Bank verification confirms who you are; document requests confirm you can afford to gamble at the level you are playing. The two checks serve different regulatory purposes.
Pay N Play and Casino Bonuses: What You Need to Know
Bonus eligibility at UK casinos depends on payment method, and the exclusions vary by operator. Skrill and Neteller—e-wallets often used to move money in and out of gambling sites quickly—are commonly excluded from welcome offers because operators treat them as higher fraud risk or as tools for bonus abuse. Debit cards and bank transfers typically qualify without restriction. Pay N Play deposits via Trustly, TrueLayer, or Plaid almost always qualify for bonuses because they are bank-verified payments with closed-loop withdrawal requirements, making them low-risk from the operator’s perspective.
At the eleven operators listed, Trustly deposits qualify for welcome bonuses without carve-outs. LeoVegas, Casumo, Mr Green, Unibet, Betsson, Rizk, Videoslots, William Hill, Duelz, 888 Casino, and MrQ all accept Pay N Play deposits for their headline offers. The bonus structures vary—some offer deposit matches with free spins, others offer free spins only, MrQ offers zero-wagering spins—but none exclude Trustly as a payment method. This is a practical advantage over Skrill or Neteller, which are often explicitly banned from bonus eligibility in the terms and conditions.
The catch is not the payment method; it is the wagering requirements. UK casinos impose rollover requirements on bonus funds and free spin winnings to prevent immediate withdrawal. Standard wagering in the UK market sits at 35–40x the bonus amount. A £100 bonus at 35x wagering requires £3,500 in total bets before the bonus converts to withdrawable cash. Slot spins typically contribute 100% to wagering; table games like blackjack and roulette contribute 10–20% or are excluded entirely. Maximum bet per spin while wagering is usually capped at £5 to prevent large single-bet rollover manipulation. Time limits—typically 7 to 30 days to complete wagering—add pressure.
Videoslots and MrQ stand out for player-friendly terms. Videoslots dropped its welcome bonus wagering to 10x in 2024, the lowest in the UK. A £50 bonus requires £500 wagering, not £1,750 or £2,000. MrQ eliminates wagering entirely: free spin winnings are credited as cash with no rollover. Both operators accept Trustly deposits for these offers. If you have been frustrated by high-wagering bonuses that expire before you clear them, these two are structurally different.
The flip side: smaller headline offers. Videoslots offers £50 with 10x wagering. Competitors offer £100–£200 with 35–40x wagering. Which is better depends on your play style. If you play casually and rarely clear high wagering, the Videoslots or MrQ model converts more bonus value into withdrawable cash. If you play high-volume and clear wagering easily, a larger bonus with standard rollover might deliver more total value. The payment method—Trustly—qualifies for both; the choice is between bonus structures, not eligibility.
Some casinos require manual claiming even when the payment method qualifies. You deposit via Trustly, the funds credit, and the bonus does not appear automatically. You open a support chat or click a “claim bonus” button in your account dashboard. This is intentional friction: it ensures you actively consent to the bonus rather than having it applied by default with wagering restrictions you did not want. If you prefer to play with cash balance only—no wagering, no restrictions—some operators let you decline the bonus during deposit or claim it later if you change your mind. Check the cashier interface before completing your first Trustly deposit; most sites offer an opt-in checkbox.
Do Pay N Play deposits qualify for casino bonuses in the UK?
Yes, Pay N Play deposits via Trustly, TrueLayer, or Plaid qualify for casino bonuses at all eleven operators listed in this guide. Unlike Skrill and Neteller, which are commonly excluded, bank-based payments are treated as low-risk and eligible for welcome offers. Wagering requirements and claiming procedures vary by operator; always check bonus terms before depositing.
Bonus abuse is the historical reason Skrill and Neteller face exclusions. A player could create multiple accounts, deposit via e-wallet, claim the welcome bonus on each, clear minimal wagering, withdraw to the wallet, and repeat. Closed-loop bank payments make this harder: Trustly ties your account to a verified bank account in your name, and UK regulations prohibit operators from opening multiple accounts for the same person. The GamStop register further prevents multi-account abuse by flagging duplicate identities across all UKGC-licensed sites. The structural barriers make Pay N Play deposits safer from the operator’s perspective, which is why they remain bonus-eligible even as e-wallets face restrictions.
Bonus terms are still worth reading in full before claiming. Maximum bet caps during wagering, game contribution rates, time limits, and withdrawal restrictions all affect whether the bonus is worth taking. A 35x wagering requirement with a 30-day time limit and £5 max bet is standard. A 40x requirement with a 7-day limit is harder to clear. A 10x requirement with the same 30 days is dramatically easier. Trustly eligibility gets you through the door; the terms determine whether you want to walk in.
The Legal Framework: UKGC Rules and Pay N Play
The UK Gambling Commission operates under the Gambling Act 2005, which established the modern regulatory framework for all forms of gambling in Britain. The UKGC issues remote gambling licences to casino operators and enforces compliance through Licence Conditions and Codes of Practice, a detailed rulebook covering everything from customer verification to advertising standards. Licence Condition 17, which governs customer identity verification, is the most relevant to Pay N Play.
Condition 17 requires operators to verify the identity and age of every customer before that customer is permitted to gamble. The verification must confirm name, date of birth, and address, and must be completed using reliable, independent sources. Acceptable methods include electronic verification against credit reference agencies, checks against government databases, or manual document review. The key word is “before”: operators cannot allow a customer to deposit, play, and then verify before withdrawal. Verification must happen upfront. This eliminated the old “deposit and play, verify later” model that some operators used in the early 2010s.
Trustly’s bank-ID verification satisfies Condition 17 by leveraging the KYC checks your bank has already performed. When you open a UK bank account, the bank verifies your identity against government databases, credit references, and physical documents. The bank holds that verified data. The Open Banking framework, implemented under the Payment Services Regulations 2017 as the UK’s transposition of the EU’s PSD2 directive, allows third-party payment providers like Trustly to request access to that verified data with your consent. When you authenticate a Trustly payment, you are consenting to both the transaction and the sharing of your verified identity with the recipient. Trustly receives your name, date of birth, and address from the bank, confirms they match the bank’s records, and forwards them to the casino. The casino receives identity data it can trust because it comes from a regulated financial institution that has already verified you.
This satisfies the UKGC’s requirement for “reliable, independent” verification. The casino does not need to ask you to upload a passport or driving licence because the bank has already done the equivalent check. The automated flow meets the regulatory standard while removing manual friction. But it does not eliminate the account. Condition 17 requires the operator to hold the verified data in a customer account, and Social Responsibility Code 3.4.1 requires integration with GamStop. The casino must create a full player account, check your details against the GamStop register, and ensure you are not self-excluded. If you are on GamStop, the verification will fail and you cannot gamble at that casino. The system works as designed.
Why True “No Registration” Doesn’t Exist in the UK
Sweden and Finland, where Pay N Play originated, have different regulatory structures. The Swedish Gambling Authority and the Finnish gambling regulator permit session-based accounts where a player’s data is held temporarily for the session and can be purged afterward if the player does not return. This enables a genuinely registration-free experience: you deposit, play, withdraw, and leave no persistent account unless you choose to create one. The UK does not permit this. UKGC rules require persistent accounts with full transaction history, ongoing monitoring for problem gambling indicators, and durable integration with GamStop.
The practical consequence: UK Pay N Play casinos create accounts for you whether you see the form or not. The account is persistent. It holds your balance, transaction log, deposit limits, and play history. If you trigger affordability checks or responsible gambling thresholds, the operator can review your history and intervene. If you self-exclude via GamStop, your account is flagged and you cannot open another at any UKGC-licensed site. The “no registration” pitch refers to the user-facing experience—no form-filling—not the backend reality. The backend holds a full account subject to all regulatory obligations.
This is not a workaround or a loophole. It is the UKGC’s deliberate design. The regulator wants operators to know their customers, monitor for harm, and enforce self-exclusion consistently. Anonymous or session-only gambling is incompatible with those goals. Trustly’s contribution is automating the verification step so it feels instant to the user, but the account structure remains identical to a traditional registration. When operators market Pay N Play in the UK, they are marketing speed and convenience, not anonymity.
GamStop Integration Requirements
GamStop is the UK’s national self-exclusion register, launched in 2018 and made mandatory for all UKGC-licensed operators. When a player self-excludes via GamStop, their details are shared with every licensed operator in real time. The operator must block that player from opening new accounts, accessing existing accounts, and receiving marketing. The block lasts for a minimum of six months and can be extended to five years. Removal before the chosen period expires is not permitted; the player must wait out the term.
Every UK Pay N Play casino integrates with GamStop. When you authenticate a Trustly deposit, the casino receives your verified identity and checks it against the GamStop register before creating your account or allowing you to play. If you are registered on GamStop, the check fails and the transaction is blocked. You do not get an account; you do not get to deposit. The system prevents gambling before it starts. This is mandatory for UKGC licence holders; there are no exemptions.
Some offshore casinos advertise “Pay N Play without GamStop” targeting UK players. These operators hold licences from jurisdictions like Curaçao, Malta (for non-UK players), or Costa Rica and do not integrate with the UK’s self-exclusion system. Playing at these sites as a UK resident is not illegal for the player, but the sites themselves operate without UKGC authorisation and are not subject to UK consumer protections. If a dispute arises—unpaid winnings, unfair terms, technical glitches—you have no recourse through the UKGC. The Alternative Dispute Resolution schemes and ombudsman services that apply to licensed operators do not cover offshore sites. The “no GamStop” angle is a feature for players who have self-excluded and want to circumvent their own block, but it comes at the cost of regulatory protections.
For players not on GamStop, this is irrelevant. Every UK-licensed Pay N Play casino on this page integrates with the register, checks you against it, and proceeds normally if you are not excluded. The check happens in the background during the Trustly verification flow. You do not see it; you do not interact with it. It is a silent safeguard ensuring that self-exclusion works across all licensed operators without requiring manual enforcement.
Affordability Checks and Document Requests
Licence Condition 3.5.3, which governs customer interaction and safer gambling, requires operators to monitor customer activity for indicators of gambling-related harm and to intervene when those indicators appear. The UKGC provides guidance on thresholds: significant losses relative to deposit patterns, time spent gambling, rapid escalation in stakes, chasing behavior. Operators must build systems to detect these patterns and respond with reality checks, limit suggestions, or enhanced due diligence requests.
Affordability checks sit within this framework. If a customer deposits and loses amounts that appear disproportionate to typical income levels, the operator must assess whether the customer can afford those losses without suffering harm. The assessment can be automated using modeled income data from credit reference agencies, Office for National Statistics income distribution tables, and postcode-level socioeconomic data. For borderline cases or higher-value customers, the operator must request direct evidence: recent bank statements, payslips, tax returns, or other documentation showing income and financial position.
Trustly verification does not substitute for affordability checks. The bank confirms your identity and that the account is yours; it does not report your income to the casino. The casino must make its own assessment, and for customers who exceed thresholds, that means requesting documents. A £1,000 deposit might pass automated affordability checks for a customer in a high-income postcode with clean credit references. The same deposit from a customer in a low-income area or with adverse credit might trigger a manual review and a document request before further deposits are allowed.
This is the UKGC’s harm-prevention model at work. Pay N Play speeds up identity verification but does not eliminate the need for financial verification at higher stakes. If you plan to play at levels where a single session could cost hundreds of pounds, expect the casino to ask questions about your income and ability to afford losses. This applies equally to traditional registration and to Pay N Play; the payment method affects the speed of onboarding, not the rigor of ongoing monitoring.
Is Pay N Play safe and legal at UK casinos?
Yes, Pay N Play via Trustly is both safe and legal at UKGC-licensed casinos. Trustly is an authorized payment institution under UK and EU regulations. The Open Banking framework it uses is mandated by UK law. Every Pay N Play casino listed in this guide holds an active UKGC licence and is subject to the Gambling Commission’s consumer protection rules, including dispute resolution and responsible gambling requirements.
Can I use Pay N Play if I’m registered with GamStop?
No. All UKGC-licensed casinos, including those offering Pay N Play, integrate with the GamStop self-exclusion register. If you are registered on GamStop, your Trustly verification will be checked against the register and blocked before you can deposit or play. The system prevents access at the point of account creation. Offshore casinos that advertise “no GamStop” operate without UKGC licences and lack UK consumer protections.
The UKGC has signaled further tightening of affordability checks in recent consultations, with proposals for stricter thresholds and faster intervention timelines. These changes, if implemented, will affect all operators equally regardless of payment method. Pay N Play does not insulate you from regulatory scrutiny; it automates the front-end verification, but the back-end monitoring remains as rigorous as at any traditional casino.
Alternatives to Pay N Play for UK Players
Trustly and its equivalents are not the only fast payment options at UK casinos. The open-banking category includes multiple providers offering functionally identical experiences under different brand names. E-wallets provide a different speed-versus-privacy trade-off. Traditional debit cards remain the most universal option. Understanding where Pay N Play sits in the broader payment landscape helps clarify when it is the best choice and when an alternative might suit better.
TrueLayer and Plaid are direct competitors to Trustly in the open-banking space. All three connect via the same UK Open Banking APIs, authenticate via your bank app, and settle via Faster Payments. The user experience is identical: pick your bank, log in, approve the payment. The difference is which payment service provider the casino has integrated on the backend. LeoVegas uses TrueLayer, PokerStars uses Plaid, bet365 uses Trustly. From your perspective, these are interchangeable. If a casino lists “Instant Bank Transfer” or “Pay by Bank” without a brand name, it is almost certainly one of these three providers under the hood.
The advantage over Trustly-branded Pay N Play is that TrueLayer and Plaid are sometimes available at casinos that do not market themselves as “Pay N Play” sites. You get the same speed—instant deposits, fast withdrawals via Faster Payments—without the registration-automation angle. This matters if you prefer to set a username and password manually rather than relying on deposit-triggered logins. The payment speed is what you are optimizing for; the account creation method is a secondary preference.
PayPal is the most recognized e-wallet in the UK and is accepted at many UKGC-licensed casinos, though not universally. Deposits via PayPal are instant. Withdrawals typically land in your PayPal balance within hours, and you can then transfer to your bank in one additional step. The speed is comparable to Trustly once you account for the wallet-to-bank transfer leg. The privacy angle is different: your bank statement shows a PayPal transaction, not the casino’s name directly. For players who prefer not to have gambling transactions visible on their primary bank statement, this is a meaningful distinction. The downside is that PayPal, like Skrill and Neteller, is sometimes excluded from casino bonuses. Not always, but often enough that you must check terms before depositing if you care about bonus eligibility.
Skrill and Neteller offer similar e-wallet functionality with slightly different fee structures and bonus eligibility profiles. Both are widely accepted at UK casinos. Both settle deposits instantly and withdrawals within hours. Both are frequently excluded from welcome bonuses. If you already use Skrill or Neteller for other purposes—poker sites, sports betting, international payments—they integrate smoothly into casino play. If you are choosing a payment method solely for UK casino use, Trustly or PayPal are usually better because they do not carry the same bonus exclusions.
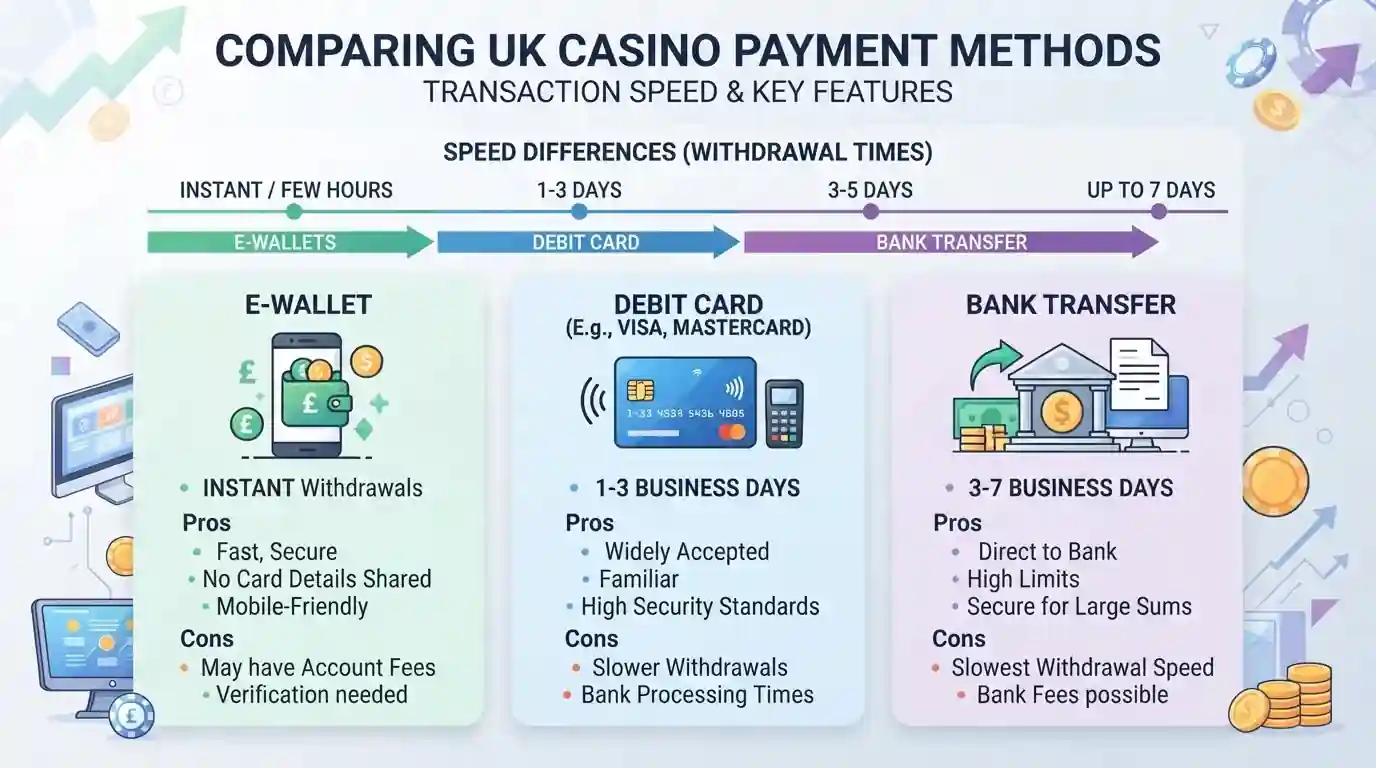
Debit cards remain the default at most UK casinos. Visa and Mastercard debit are universally accepted. Deposits are instant or near-instant, though card authorization can occasionally take a few minutes if the issuing bank’s fraud checks flag the transaction. Withdrawals to debit cards take longer than open banking or e-wallets—typically one to three business days—because card settlements go through the card scheme’s clearing process rather than Faster Payments. The convenience is universality: every UKGC-licensed casino accepts debit cards, and you do not need to integrate a new payment method. The drawback is withdrawal speed. If you prioritize fast payouts, open banking or e-wallets are structurally faster.
Credit cards were banned for gambling deposits in the UK in April 2020, so they are not an option at any licensed casino. The ban was a harm-reduction measure aimed at preventing gambling with borrowed money. Debit cards, which draw from your own funds, remain unrestricted.
Traditional bank transfers—initiated via your bank’s online banking rather than through an Open Banking API—are the slowest option but carry the highest per-transaction limits. If you need to deposit £10,000 or more, traditional bank transfer is sometimes the only method that accommodates the amount. Deposits take one to three business days to clear. Withdrawals take the same. This is a high-roller or occasional-use method, not a default for regular play. The speed trade-off is severe compared to Trustly, but the lack of per-transaction caps makes it necessary for large movements.
| Method | Speed (Deposit / Withdrawal) | Pros | Cons |
|---|---|---|---|
| Trustly / TrueLayer / Plaid | Instant / Hours to same-day | Fastest withdrawals, bonus-eligible, bank-verified | First withdrawal may trigger documents |
| PayPal | Instant / Hours (to wallet) | Privacy (casino name not on bank statement), widely recognized | Sometimes excluded from bonuses, extra step to bank |
| Skrill / Neteller | Instant / Hours | Fast, international use, separate balance | Often excluded from bonuses, fees on some transactions |
| Debit Card | Instant / 1–3 business days | Universal acceptance, no new setup | Slower withdrawals, card scheme delays |
| Bank Transfer | 1–3 days / 1–3 days | No transaction limits, high-value friendly | Slow in both directions, not for regular use |
The choice depends on your priorities. If withdrawal speed is paramount, Trustly and its equivalents are unmatched. If you want a privacy layer between your bank statement and the casino, PayPal makes sense despite occasional bonus exclusions. If you value universality and do not mind waiting a few days for withdrawals, debit cards work everywhere. If you are moving large sums infrequently, traditional bank transfer handles amounts that other methods cap.
Other Open Banking Options (TrueLayer, Plaid)
TrueLayer powers open-banking payments at LeoVegas, Virgin Games, and several smaller UK casinos. Plaid powers PokerStars and is expanding to other operators. Both offer the same technical flow as Trustly: you pick your bank, authenticate in your app, and the payment settles via Faster Payments in seconds. The difference is purely backend integration. If you see “Pay by Bank” or “Instant Bank Transfer” in a cashier, it is likely TrueLayer or Plaid. The experience is indistinguishable from Trustly.
The advantage of knowing this is that you can recognize fast bank payments even when they are not labeled “Pay N Play.” Some casinos integrate TrueLayer for speed but retain traditional registration forms rather than automating account creation. You still get instant deposits and fast withdrawals; you just fill in a form upfront. If the registration-free angle of Pay N Play does not matter to you—if you are comfortable creating a username and password manually—then TrueLayer or Plaid at a non-Pay-N-Play casino delivers the same payment speed without the deposit-triggered login model.
PayPal and E-Wallets
PayPal is accepted at a significant minority of UK casinos, though not at all eleven Pay N Play operators listed earlier. LeoVegas, Casumo, and others accept PayPal alongside Trustly; some smaller operators offer PayPal but not open banking. Deposits via PayPal are instant: you log in to your PayPal account, authorize the payment, and funds credit immediately. Withdrawals land in your PayPal balance within hours, typically faster than debit card withdrawals. You then transfer from PayPal to your bank in a separate step, which takes one business day via standard transfer or is instant via PayPal’s “Instant Transfer” feature for a small fee.
The privacy advantage is real. Your bank statement shows a PayPal transaction, not the casino’s merchant name. For players who share bank accounts with family or who prefer discretion, this matters. The bonus eligibility varies: some casinos accept PayPal deposits for bonuses, others exclude it alongside Skrill and Neteller. Check terms before depositing if a welcome offer is part of your plan.
Skrill and Neteller operate similarly. Both are e-wallets designed originally for international money transfers and adopted heavily by the gambling industry. Deposits are instant; withdrawals to the wallet take hours; wallet-to-bank transfers add one more day. Both carry fees on certain transactions—currency conversion, card deposits to the wallet, transfers to unverified accounts. For UK-only casino use, these fees often outweigh the benefits. For players who use Skrill or Neteller across multiple gambling sites or internationally, the wallet becomes a central hub. Bonus exclusions are near-universal: most UK casinos ban Skrill and Neteller from welcome offers due to historical bonus abuse.
Traditional Debit Cards
Visa and Mastercard debit cards are the most universal payment method at UK casinos. Every UKGC-licensed operator accepts them. Deposits are instant or near-instant, though occasional fraud-check delays can stretch authorization to a few minutes. Withdrawals take one to three business days because card payments settle through the card scheme’s clearing process rather than Faster Payments. You request the withdrawal; the casino approves it; the card scheme processes the return; your bank credits your account. The multi-step process is slower than open banking but more reliable than it used to be—most UK casinos now process card withdrawals within 24–48 hours rather than the three-to-five days common a decade ago.
Debit cards qualify for bonuses without exclusions. No new account setup is required; you enter the card details in the cashier and start playing. The simplicity is the main draw. The withdrawal speed is the main drawback. If you do not mind waiting a day or two for payouts, debit cards work fine. If you want your winnings in hours, open banking is structurally faster.
Why Some Operators Dropped Pay N Play or Never Adopted It
Pay N Play was marketed aggressively to UK operators between 2019 and 2021 as the future of frictionless gambling. Trustly pitched it as a competitive differentiator: faster onboarding, higher conversion, fewer abandoned registrations. Several operators—LeoVegas, Casumo, Rizk, Videoslots—adopted it and promoted it heavily. Then adoption plateaued. By 2022, the rate of new Pay N Play launches in the UK had slowed to a trickle. Some operators integrated Trustly for deposits and withdrawals but skipped the automated-registration angle entirely. Why?
The UKGC’s evolving compliance requirements made the “no registration” model harder to justify. As affordability checks tightened and customer interaction requirements expanded, operators needed more upfront data on customers, not less. The Pay N Play model automates identity verification but provides minimal behavioral data at the point of onboarding. Traditional registration forms let operators collect additional signals—self-reported income, employment status, gambling history, reason for playing—that feed into risk models. Skipping the form means relying entirely on third-party data sources and post-onboarding monitoring. For high-risk or high-value customers, this creates compliance gaps.
GamStop integration added complexity. The self-exclusion check must happen before any gambling, and it must be reliable. Trustly’s bank-ID verification provides the necessary identity data for the check, but the integration requires tight coordination between the payment flow, the casino’s backend, and the GamStop API. If any step fails or times out, the player cannot proceed. Some operators found the error-handling and fallback logic more complex than running a traditional registration form with a separate GamStop check.
Bonus abuse was another concern. The “deposit to log in” model made it harder to enforce single-account rules. A player could use different bank accounts—joint accounts, accounts in a partner’s name with permission, business accounts—to create multiple sessions and claim welcome bonuses repeatedly. The UKGC’s rules prohibit multiple accounts, and GamStop checks catch duplicate identities, but enforcement is harder when the onboarding is fully automated and no username is created. Operators who had dealt with bonus abuse at scale were cautious about removing friction that also served as a barrier to serial claimers.
The result is that UK Pay N Play in 2026 is a mature but niche offering. The operators who adopted it early—LeoVegas, Casumo, Videoslots, MrQ—continue to support it and benefit from faster onboarding. Most other operators integrated Trustly or TrueLayer for payment speed but retained traditional registration for compliance and data collection. The Swedish vision of genuinely registration-free gambling never fully transplanted to the UK regulatory environment. What remains is fast bank payments with automated identity checks, which is valuable but not revolutionary.
Game Types and Mobile Compatibility
Every UK casino that accepts Pay N Play offers the standard game library: slots, live dealer tables, and virtual table games. The payment method does not dictate game availability. LeoVegas, Casumo, and Videoslots all offer 1,000+ slots from major providers like NetEnt, Microgaming, Play’n GO, Pragmatic Play, and dozens of smaller studios. Live dealer sections at these operators run on Evolution, Pragmatic Live, or Playtech Live platforms, covering roulette, blackjack, baccarat, poker variants, and game-show titles like Crazy Time and Monopoly Live. Virtual table games—RNG blackjack, roulette, video poker—are available at all operators. Specialty games like scratch cards, keno, and instant-win titles appear at most but not all.
The game library depth varies by operator size and content partnerships. Videoslots leads with 4,000+ slots from 100+ providers. Casumo offers 3,500+ games. Smaller operators like MrQ focus on 500 curated mainstream titles rather than exhaustive catalogues. The depth difference matters if you chase obscure slots from niche studios; for players who stick to popular titles like Starburst, Book of Dead, or Gonzo’s Quest, every operator covers the essentials.
Mobile compatibility is universal. Every UKGC-licensed casino listed operates on mobile-optimized web platforms, and most offer dedicated iOS and Android apps. LeoVegas pioneered mobile-first design and still leads on app quality, but Casumo, Unibet, Betsson, and 888 Casino all deliver functional mobile experiences. Pay N Play deposits work identically on mobile: you tap deposit, select Trustly, choose your bank, and authenticate in your bank’s app. The flow is arguably smoother on mobile than desktop because the bank authentication step stays within the mobile environment rather than requiring a desktop-to-mobile handoff.
App-based casinos sometimes deliver slightly faster performance—preloaded assets, local caching, push notifications for bonuses and withdrawals—but the mobile web experience at most UK operators is good enough that downloading an app is optional rather than necessary. If you play primarily on mobile, LeoVegas, Casumo, or 888 Casino are safe bets. If you switch between devices, the mobile web versions at all eleven operators handle the transition smoothly.
Pay N Play in Context: What Happened and What’s Next
Pay N Play entered the UK market in 2019 as a Swedish import with a compelling pitch: no forms, no delays, instant play. Trustly had proven the model in Sweden and Finland, where regulators permitted session-based accounts and lighter verification requirements. UK operators saw an opportunity to reduce onboarding friction and improve conversion rates. Early adopters like LeoVegas and Casumo integrated Trustly, promoted the “no registration” angle heavily, and saw meaningful upticks in first-time depositors. Affiliate sites amplified the messaging. By 2020, Pay N Play was positioned as the future of UK online casinos.
Then reality set in. The Gambling Commission did not permit session-based accounts. Operators had to create full persistent accounts with GamStop integration and transaction monitoring, which meant the “no registration” claim was marketing shorthand rather than operational fact. Players who expected genuinely anonymous gambling found themselves with accounts, deposit limits, and affordability checks just like at traditional casinos. The speed advantage was real—onboarding took two minutes instead of ten—but the regulatory obligations were unchanged.
Affordability checks tightened in 2021 and 2022 as the UKGC responded to political pressure over gambling harm. Operators faced stricter requirements to assess whether customers could afford their losses and to intervene proactively when risk indicators appeared. This meant collecting more data upfront, not less. The Pay N Play model, which minimized upfront data collection in favor of speed, sat uneasily with the trend toward enhanced due diligence. Some operators integrated Trustly for payment speed but retained traditional registration forms to capture the data they needed for compliance. Others stuck with Pay N Play but added document requests and affordability questions earlier in the customer journey, which eroded the frictionless appeal.
By 2023, the UK Pay N Play market had plateaued. The operators who adopted it early continued to support it, but few new entrants launched Pay N Play offerings. The focus shifted to open banking as a payment rail—instant deposits, fast withdrawals—without the automated-registration angle. TrueLayer and Plaid gained traction as alternatives to Trustly, and casinos marketed “instant bank transfer” or “pay by bank” without the “no registration” framing. The underlying technology was identical; the messaging was less ambitious.
The Rise and Plateau of Pay N Play in the UK (2019–2026)
2019: Trustly partners with LeoVegas and Casumo to launch Pay N Play in the UK. Early marketing emphasizes speed and lack of forms. Conversion rates improve compared to traditional registration flows.
2020: Rizk, Videoslots, and smaller operators adopt Pay N Play. Affiliate sites promote it as a major differentiator. The COVID-19 lockdowns drive online gambling growth, and the simplified onboarding captures new players who might have abandoned traditional registration forms.
2021: The UKGC issues guidance on affordability checks and customer interaction, requiring operators to assess financial risk more proactively. Operators realize that automated registration via bank verification provides minimal behavioral data for risk assessment. Some begin layering additional questions onto the Pay N Play flow, reducing the speed advantage.
2022: GamStop integration and AML compliance dominate operator discussions. Pay N Play’s automated model complicates both. New UK casino launches increasingly skip Pay N Play in favor of Trustly or TrueLayer for payments only, retaining traditional registration for compliance data collection.
2023–2026: The UK Pay N Play market stabilizes with a core group of operators—LeoVegas, Casumo, Videoslots, MrQ, William Hill, 888 Casino—continuing to support it. Adoption among new entrants is limited. Open banking grows as a payment method without the registration-free framing. The Swedish vision of no-account gambling remains incompatible with UK regulatory requirements.
Non-UKGC “Pay N Play” Sites: Why to Avoid Them
Offshore casinos operating without UKGC licences sometimes advertise “Pay N Play without GamStop” or “instant casinos, no UK restrictions.” These sites hold licences from jurisdictions like Curaçao, Costa Rica, or Kahnawake and target UK players who have self-excluded via GamStop or who want to avoid UK deposit limits and affordability checks. Playing at these sites is not illegal for UK residents—the Gambling Act does not criminalize players, only unlicensed operators advertising to UK customers—but it is unwise for several reasons.
No consumer protections. UKGC-licensed operators must adhere to strict rules on fairness, dispute resolution, and responsible gambling. If a dispute arises—unpaid winnings, technical glitches, bonus terms disputes—you can escalate to an Alternative Dispute Resolution service and ultimately to the Independent Betting Adjudication Service ombudsman. Offshore operators are not bound by these schemes. If the casino refuses to pay out, your recourse is limited to whatever jurisdiction issued their licence, which often provides minimal oversight.
No GamStop integration. The “no GamStop” angle is a feature for players who want to circumvent their own self-exclusion, but self-exclusion exists for a reason. If you registered on GamStop because gambling was causing harm, an offshore casino that bypasses the block is not offering freedom; it is offering a way to undermine your own harm-reduction decision. UKGC-licensed operators are required to honor GamStop blocks. Offshore operators ignore them.
Payment risks. Offshore casinos often use payment processors that operate in legal grey areas or charge higher fees. Deposits may go through smoothly, but withdrawals can be delayed, capped, or refused for spurious reasons. The lack of UK regulatory oversight means the operator faces no penalties for poor payment practices.
Tax implications. Gambling winnings are tax-free in the UK when the operator holds a UKGC licence because the operator pays tax on gross gaming revenue. Offshore operators do not pay UK tax. Technically, winnings from offshore gambling may be taxable as miscellaneous income, though HMRC enforcement of this is rare and the reporting burden falls on the player. The risk is small but nonzero.
For UK players not on GamStop and not chafing against UK deposit limits, offshore “Pay N Play” casinos offer no advantage over UKGC-licensed operators. The payment speed is identical—offshore sites use Trustly or similar providers just like licensed casinos—but the consumer protections and regulatory oversight are absent. The eleven operators listed in this guide are licensed, monitored, and bound by rules that protect players. That is worth more than the marginal convenience of bypassing a self-exclusion you chose to impose.
Which UK Banks Support Pay N Play and Trustly?
All major UK banks support Open Banking APIs, which means they work with Trustly, TrueLayer, Plaid, and other open-banking payment providers. The list includes Barclays, HSBC, Lloyds Banking Group (Lloyds, Halifax, Bank of Scotland), NatWest Group (NatWest, Royal Bank of Scotland, Ulster Bank), Santander UK, Nationwide Building Society, TSB, First Direct, and the major digital banks like Monzo, Starling Bank, and Revolut. If your bank offers online or mobile banking, it almost certainly supports Open Banking.
A handful of smaller building societies, credit unions, and regional banks do not yet support Open Banking APIs or support them only partially. If you bank with a very small institution and the Trustly payment window does not list your bank, you will need to use an alternative payment method. This is rare; coverage in the UK is above 95% of current accounts.
Business accounts and joint accounts work with Pay N Play as long as the bank supports Open Banking for those account types. Most do. If you use a business account, the casino may flag it for enhanced due diligence because business accounts carry higher money-laundering risk. Joint accounts raise questions about which account holder is gambling. Some casinos request additional documentation when they detect a joint account or business account in the Trustly data. The safest approach is to use a personal current account in your name only.
If your bank appears in the Trustly selection window during a deposit, it works. If it does not appear, your bank either does not support Open Banking or Trustly has not yet integrated it. In that case, use a debit card or PayPal instead. Open Banking coverage in the UK continues to expand, and smaller banks are gradually integrating, but full coverage is not yet universal.
The speed of Faster Payments settlement also varies slightly by bank. Most UK banks process Faster Payments 24/7, so Trustly withdrawals land in your account at any time of day. A few smaller banks only process Faster Payments during business hours, which means a withdrawal initiated on a Saturday night might not land until Monday morning. This is a bank limitation, not a Trustly limitation. If same-day withdrawals matter to you and you bank with a smaller institution, check whether your bank supports 24/7 Faster Payments. The major banks all do.
Trustly and its equivalents are legally sound, widely adopted, and structurally faster than alternatives. For UK players in 2026, they represent the best balance of speed, security, and regulatory compliance. The “Pay N Play” framing is partly marketing—accounts exist, GamStop applies, affordability checks still happen—but the speed gain is real, and the operators who support it are among the most established in the UK market.
Casino Deposit Methods UK 2026 — Cards, E-Wallets & More
Content created by the «casinomoneyg» team